 View details
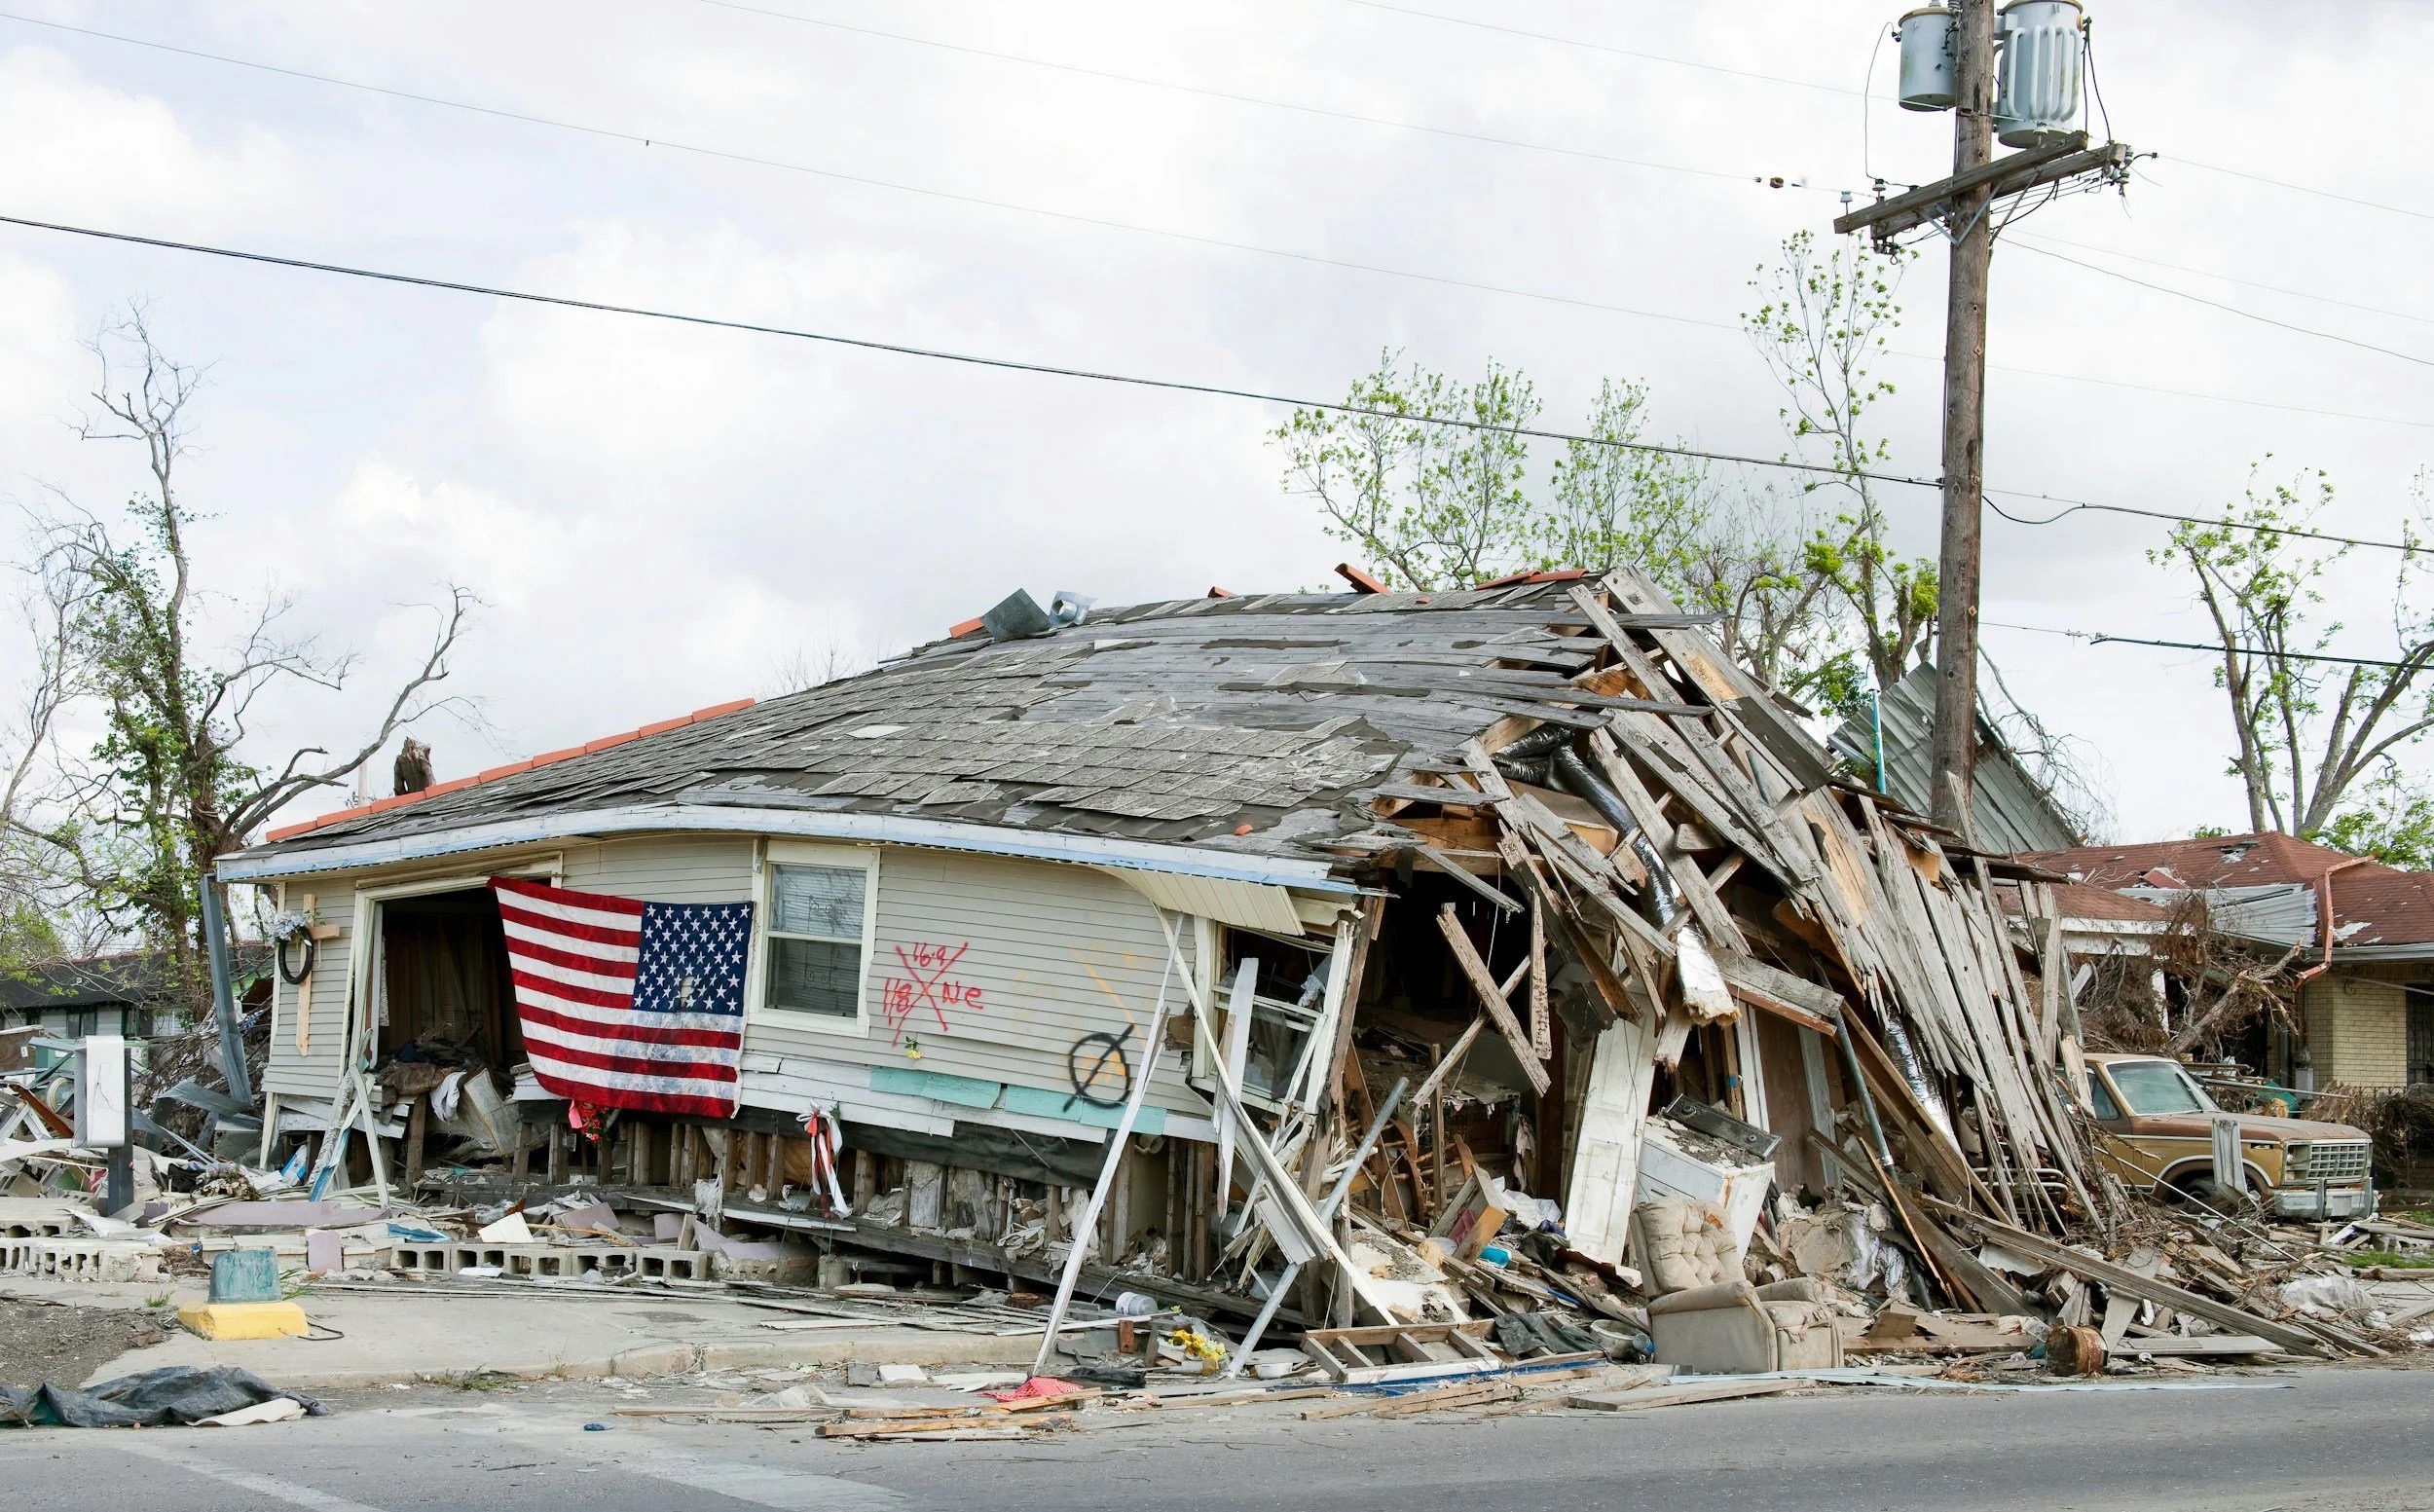
Tornado Damage
Tornado losses can affect nearly every part of a structure, and the obvious damage is often only the beginning.
- Roof and siding failure
- Broken windows and openings
- Foundation or framing movement
Licensed Ohio Public Adjuster #1367111
Call (419) 504-1601We wish that billion-dollar companies wouldn't take advantage of everyday hardworking Americans suffering from loss. Unfortunately, the current systems in place in regards to claim handling procedures, allow for systemic underpayments by insurance companies. If you are dealing with an insurance group offering you only a portion of what your policy should provide, you need to call Keathley Claims Consultants. We've worked with and for large corporations, so we are well-versed in their tricks and ready to push back if they try anything. Don't hesitate to call us today at (419) 504-1601 to start your claim process.
If you need an Ohio public adjuster for a fire, wind, hail, or other property claim, start there. If a repair estimate and the claim file are getting mixed together, see public adjuster vs contractor.
What property damage have you experienced and or currently dealing with?
Common Claim Types
Every property loss has a different path. These quick summaries show the kinds of damage each peril can create, and why early documentation matters when presenting your claim.
View details
Tornado losses can affect nearly every part of a structure, and the obvious damage is often only the beginning.
 View details
Wind and hail can leave a property looking mostly intact while still creating hidden roof, siding, and water intrusion issues.
 View details
Fire claims often include more than burned materials. Smoke, soot, odor, and contamination can spread through untouched rooms.
 View details
Water can move quickly through floors, walls, cabinets, and insulation, creating damage that worsens when it is not documented early.
 View details
A broken pipe can release a large volume of water fast, especially during freezing weather or when the leak goes unnoticed.
 View details
Sewer backups can create serious cleanup and safety concerns because wastewater can carry bacteria, odor, and contamination.
Claim Focus
KCC helps homeowners, landlords, businesses, and property owners understand the next step when a claim estimate, denial, or appraisal issue does not make sense.
Wind and hail claims can involve roof damage, siding damage, gutters, soft metals, interior leaks, matching, repairability, storm-date proof, and underpaid repair estimates.
Learn moreWind claims can involve lifted shingles, missing roofing, siding damage, storm-created openings, interior water damage, and disputes over whether damage is old or storm-related.
Learn moreHail claims often require careful documentation of roofing, siding, gutters, downspouts, window wraps, soft metals, and hidden interior issues after storm damage.
Learn moreFire claims can include burn damage, smoke spread, soot, odor, contents, cleanup, HVAC contamination, emergency services, and additional living expense documentation.
Learn moreWhen the carrier accepts coverage but the number is still too low, insurance appraisal may help resolve amount-of-loss disputes involving fire, wind, hail, roof, siding, and other property damage.
Learn moreReview low carrier estimates for missing fire, smoke, wind, hail, roof, siding, pricing, depreciation, supplement, and appraisal-fit issues.
Learn moreCompare contractor estimates, carrier estimates, supplements, repair scope, payment math, and appraisal-fit issues when the insurance number does not match the repair path.
Learn moreOrganize fire, smoke, wind, hail, roof, siding, payment, denial, delay, and appraisal documents before deciding whether the file needs public adjusting support, a supplement, or appraisal review.
Learn morePriority Regions
Start with the region closest to the property, then choose the claim issue that fits.
Local claim review and public adjusting support from a team based in Wellington.
View areaClaim support for policyholders across the state.
View areaAppraisal support when coverage is accepted but the claim value is disputed.
View areaCentral Ohio claim review and public adjusting support.
View areaSupport for wind-related roof, siding, and interior damage disputes.
View areaSupport for hail-related exterior damage and low estimate disputes.
View areaSupport for fire, smoke, cleanup, contents, and repair scope disputes.
View areaClaim Document Checklist
A stronger claim review starts with the right documents. These files help separate missing documentation from coverage issues, estimate problems, and amount-of-loss disputes that may need appraisal review.
Save fire department reports, cause and origin notes, smoke and soot photos, mitigation invoices, contents lists, storage invoices, rebuild estimates, and additional living expense records.
Review related helpSave storm date information, roof slope photos, lifted or missing shingle evidence, siding and fascia photos, interior leak documentation, contractor findings, and carrier wear-and-tear language.
Review related helpSave photos of roof impacts, siding cracks, gutters, downspouts, vents, window wraps, screens, soft metals, collateral damage, and any cosmetic-damage or below-deductible position.
Review related helpSave the policy appraisal language, carrier estimate, competing estimates, invoices, photos, disputed line items, pricing support, mitigation records, and repairability or matching documentation.
Review related helpSave the complete claim timeline, carrier letters, estimates, payment records, photos, videos, reports, contractor notes, denial language, supplement responses, and appraisal-related documents.
Review related helpWhich Claim Path Fits?
The right next step depends on whether the problem is documentation, denied storm damage, missed fire or smoke scope, a cosmetic hail position, or a covered amount-of-loss dispute.
Claim Guides
These guides explain common claim problems and when documentation, public adjusting, estimate review, or appraisal support may help.
A practical guide to appraisal for underpaid fire, smoke, wind, hail, roof, siding, water, and storm property claim valuation disputes.
Read guideCompare whether an Ohio property claim needs public adjusting, insurance appraisal, or attorney review before choosing the next claim path.
Read guideReview when appraisal may fit an Ohio property claim after coverage is accepted but fire, wind, hail, roof, siding, or water values remain disputed.
Read guideA practical guide to matching, repairability, discontinued materials, wind, hail, roof, siding, and appraisal disputes after an underpaid claim.
Read guideStorm claim guidance for underpaid, delayed, denied, or disputed wind and hail damage involving roofs, siding, gutters, interiors, and appraisal.
Read guideFire claim guidance covering structure damage, smoke, soot, contents, cleanup, additional living expense, delays, denials, and appraisal.
Read guideWhat Ohio policyholders should review when a carrier calls hail damage cosmetic, minor, old, below deductible, or unrelated to the storm.
Read guideHow to respond when an insurance company blames wind damage on age, wear and tear, installation, or maintenance instead of storm damage.
Read guide