Roof Hail Damage
Hail can bruise shingles, displace granules, dent vents, damage ridge caps, and affect roof accessories. A full roof review matters because small missed items can change the scope and value of the claim.
Licensed Ohio Public Adjuster #1367111
Call (419) 504-1601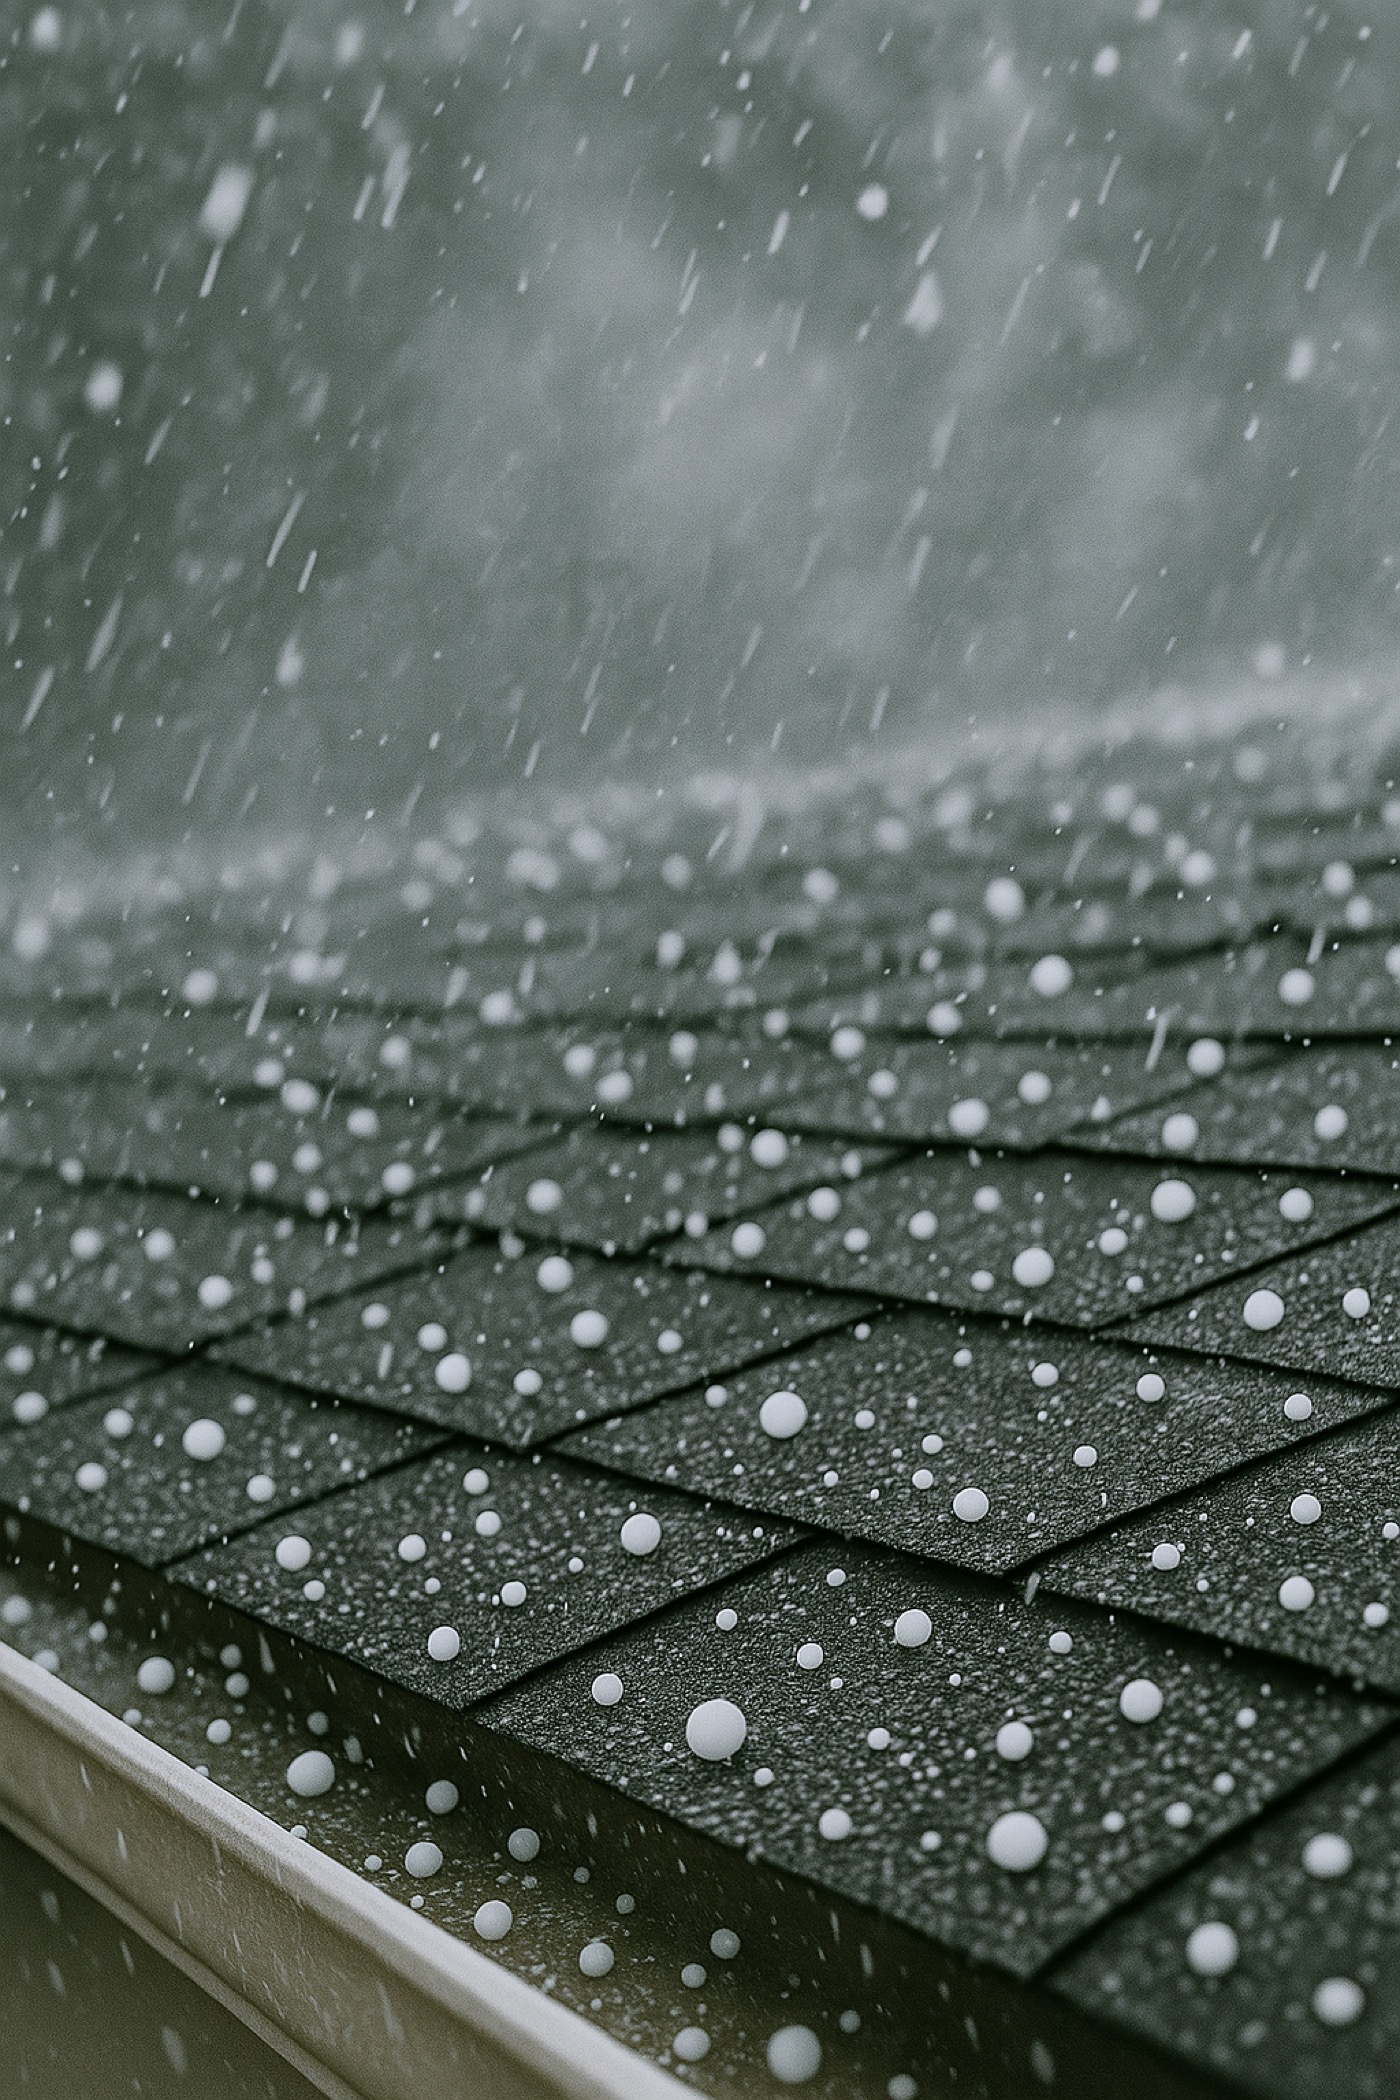
Hail damage is not always obvious from the ground, and a low insurance estimate can miss important roof, siding, gutter, window, soft metal, and interior issues. Hail can bruise shingles, damage granules, crack siding, dent gutters, affect vents and window wraps, and create disputes over whether damage is functional, cosmetic, old, or storm-related. Keathley Claims Consultants helps Ohio policyholders document hail damage and challenge incomplete, underpaid, delayed, or denied hail claims.
Ohio Public Adjuster License #1367111 | Based in Wellington, Ohio | Serving Northern Ohio and statewide Ohio | Call (419) 504-1601
Claim Help
Hail claims are frequently decided from one test square and a cosmetic label. Soft metals, siding elevations, and any leak after the storm are the items that disappear first when the inspection stays on a single roof slope.
Roof hail impacts are missed or called cosmetic.
Granule loss, bruising, and damaged accessories are not documented.
Siding cracks, chips, dents, and punctures are left out.
Gutters, downspouts, vents, windows, and soft metals are missed.
Interior water damage after the storm is treated separately.
Matching and discontinued material issues are ignored.
The estimate uses spot repairs that may not restore the property.
Pricing does not reflect local labor, material, and access conditions.
Damage KCC Reviews
Hail can bruise shingles, displace granules, dent vents, damage ridge caps, and affect roof accessories. A full roof review matters because small missed items can change the scope and value of the claim.
Vinyl, aluminum, wood, and other siding materials may show cracks, chips, punctures, or dents. Elevation-by-elevation documentation helps show the direction and severity of the hail event.
Gutters, downspouts, fascia, window wraps, screens, vents, garage doors, and other soft metals can show hail impacts that support the overall damage pattern.
A hail estimate may be too low if it ignores material matching, discontinued products, repairability, code items, or interior water damage connected to storm-created openings.
Documentation
Hail is an impact claim. The useful file shows hits on roofing, siding, and the soft metals that dent easily — plus any leak that started after the storm. One driveway photo of the roof is not that file.
Photograph bruises, fractured mat, displaced granules, and damaged pipe boots or ridge. Take shots that identify the slope. If the adjuster later relies on one test square, the rest of the roof still needs to be visible in your photos.
Walk each wall. Hail often hits one or two elevations harder. Close-ups without a wall context are easy to dismiss. Include a wider shot of the same elevation.
Soft metals and screens record hail even when someone later calls shingle marks cosmetic. These items are frequently left off the first inspection.
If it is safe, photograph hail on the ground or in a downspout. Save the date. If a leak started after the storm, photograph the ceiling and the roof area above it before stains get painted.
Matching, Code, And ALE
Hail disputes concentrate on whether impacts are “cosmetic,” whether a partial roof or wall can be matched, and whether the house stayed livable after a leak.
New shingles or siding in a hail-hit area can leave a color break on the rest of the building. A lab or database match is not the same as a reasonable appearance on the house. That distinction is the point of KCC’s ITEL article.
If hail damage supports replacing a roof system, the permitted repair may require ice barrier, underlayment, or ventilation the original roof did not have. Those items follow the policy and the code official, not the first test-square count.
Hail rarely forces a family out by itself. ALE matters when impacts open the roof or a window enough that the interior is not livable. Extra living costs need a paper trail tied to that condition.
Before Accepting The Estimate
Hail estimates often start from a test square and a “cosmetic” label. The review is whether the rest of the building and the repair reality were ever priced.
1
Ask which slopes and which walls were actually inspected. A count in one area does not describe a directional hail event on the whole house.
2
If vents and gutters are dented and the estimate only mentions shingles, the inspection was incomplete.
3
Cosmetic is a conclusion. The photos, the material, and the policy language still have to support it.
4
A small ACV figure can be the result of a thin scope, a cosmetic cut, and a depreciation holdback stacked together.
5
KCC documents hail evidence, reviews the policy, and communicates with the carrier when the first estimate treats the storm as appearance-only.
Documentation
Hail files collapse into “cosmetic” when the only records are a short estimate and a few roof photos. Keep the metals, the walls, and the letter in the same place.
1
Save the letter that calls the damage minor, old, or appearance-only. That wording is the dispute.
2
Slopes and elevations should be identifiable. Unlabeled close-ups are easy to ignore later.
3
If ITEL or a similar report was used to keep the repair small, keep that report with the contractor scope and the photos.
4
Stains, wet insulation, and the roof area above them belong in the hail file, not in a separate unexplained water claim.
Client Results
These examples are published client story summaries from KCC. Results vary by policy, damage, documentation, carrier position, deductible, depreciation, timing, and claim facts.
Wind and hail property insurance claim
$15,980.12 settlement increase and 6,166% increase
A published KCC client story describes a severe hail and wind storm claim where the settlement increased by $15,980.12 after KCC became involved.
Read client storyClaim Guides
Hail Claim Guide
This guide covers common cosmetic hail damage disputes, missed exterior items, roof and siding documentation, and when the first estimate may be incomplete.
Read Hail Claim GuideStorm Claim Guide
Review how to document storm damage, compare estimates, and preserve evidence when a hail claim involves roof, siding, gutter, window, or interior damage.
Review Storm StepsClaim Help
KCC builds a hail file from slopes, elevations, and soft metals — not from one test square. We review cosmetic language against the policy and the photos, and we deal with the carrier when the first estimate treats impact damage as appearance-only.
KCC documents the damage, reviews the policy, builds the claim position, and communicates with the carrier when the insurance estimate does not match the real loss. Ohio roofing and restoration contractors who see that same estimate gap can review how KCC works with contractor partners on disputed claims. Call (419) 504-1601.
If the insurance company accepts hail damage but the amount being offered is still too low, insurance appraisal may help resolve the value of the covered loss. Appraisal may involve disputed roof, siding, gutter, soft metal, matching, repairability, and pricing items.
Learn about insurance appraisal servicesAmount Of Loss Versus Coverage
Appraisal may help when the carrier accepts hail damage and the remaining argument is how much roof, siding, or metal work that hail requires. It is the wrong tool when the carrier says the marks do not count as covered damage.
If the policy is being read to exclude appearance-only hail, that is a coverage interpretation. An appraisal panel setting a number does not decide whether the exclusion applies.
Causation — this storm versus prior weather or wear — is not the same as pricing a roof both sides already agree is hail-damaged. Fix the causation file before anyone invokes appraisal.
Proof-of-loss and suit-limitation language is policy-specific. There is no statewide minimum time that replaces those clauses. A deadline fight is not an amount-of-loss fight.